CALGARY, Alberta (January 29, 2025) — Enverus Intelligence® Research (EIR), a subsidiary of Enverus, the most trusted energy-dedicated SaaS company that leverages generative AI across its solutions, is releasing its summary of Q4 and full-year 2024 upstream M&A activity. The year closed with $105 billion in U.S. upstream deals, the third highest total tracked by Enverus. 2024 trailed only behind a record-setting $192 billion in 2023 and just under the $108 billion booked in 2014. However, activity tumbled in the back half of the year with $9.6 billion of upstream M&A recorded in 4Q24, the fourth consecutive decline in quarterly value.
“Deal value and volume continued to drop in the final quarter of 2024 from its peak at the end of 2023 as buyers grappled with fewer M&A targets to pursue. There are also quite a few larger E&Ps working to integrate their previous deals before returning to market to acquire more,” said Andrew Dittmar, principal analyst at EIR. “Increased volatility in oil prices may have also deterred some buyers, while there is rising enthusiasm for gas and gas-weighted assets to feed burgeoning demand from LNG and data centers.”
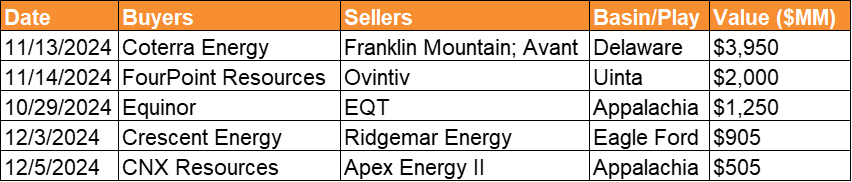
Top 5 Upstream Deals of 4Q24
The value of gas-focused M&A increased four times in 2024 compared to 2023, rising above $20 billion for the first time since 2016. The Haynesville, which is geographically best positioned to feed U.S. LNG export facilities, is a key area of interest for buyers but companies also added assets in other areas like Appalachia. International buyers, including Asian importers of LNG, are coming back to U.S. shale assets after being discouraged by poor returns a decade ago. Non-operated gas assets are likely to be highly desirable, like the position in northeast Pennsylvania Equinor acquired from EQT in Q4. Majors, which have been more recently focused on adding oil inventory, might now turn their attention to gas deals and there could even be a smaller oil-focused independent E&P that decides the best option to extend inventory is to pivot to gas.
For oil deals during Q4, buyers returned to a familiar playbook of acquiring private companies as corporate M&A waned. The largest deal of the fourth quarter was Coterra’s purchase of Avant Natural Resources and Franklin Mountain Energy in the Delaware Basin for a combined $3.95 billion. That pair of deals drove the Permian Basin to account for more than 40% of total quarterly deal value, returning the prolific region to its central position in M&A markets.
“The Permian remains at the top of the list for where buyers would prefer to add assets, but it’s also the most challenging market to buy into from the perspective of available targets and sellers’ expectations on pricing,” said Dittmar.
While Avant and Franklin Mountain were two of the last remaining Delaware Basin private opportunities, the Midland Basin still holds a few notable remaining private equity portfolio companies.
“For buyers considering acquiring one of the remaining Permian targets, the question will be if the quality and resource expansion upside is worth the price of admission. For many companies, particularly smaller sized E&Ps that have modest valuations on their own stock, the decision is likely to be to look elsewhere,” said Dittmar.
Buyers looking beyond the Permian are likely to consider a wide range of options, including more mature, established areas like the Williston Basin and Eagle Ford and emerging opportunities like the liquids window of the Utica. Mature plays are getting an uplift from revisiting developed assets with refrac and other redevelopment opportunities. Buyers are also more likely to look at extensional areas of these plays where well economics are higher on the cost curve, but assets are available at more reasonable prices. That is the strategy for Crescent Energy, the company that has been Eagle Ford’s principal recent consolidator, which acquired Ridgemar Energy in the fourth quarter of 2024 for $905 million. Buyers of these assets will look to improve economics through blocking up acreage to drill longer laterals, spacing the wells further apart or finding operational synergies that can lower costs.
“The set of remaining acquisition opportunities is largely smaller, higher up the cost curve, or both,” said Dittmar. “However, the need for scale and replacing drilled inventory means smaller E&Ps can’t simply sit out of the market. They will need to acquire these assets and have a credible plan for investors to generate returns that allow them to continue to fund dividend and buyback programs.”
A lack of opportunities to grow may eventually push smaller sized E&Ps to sell and further consolidate the industry. There were 11 mergers between public companies that exceeded $1 billion in 2023 and 2024 combined, more than double the count of the previous two years. However, the last major public company deal took place in May 2024 when ConocoPhillips acquired Marathon Oil.
“Public company M&A can provide compelling valuations for a buyer compared to private assets given the valuation on smaller sized E&Ps,” said Dittmar. “However, finding a good strategic fit between assets and getting management team alignment has gotten more challenging. The industry will continue to consolidate, but likely not at the same breakneck pace seen during the last two years.”
Private equity firms are also likely to accelerate buying activity to reload portfolios after multiple successful exits to public companies.
“A track record of successful recent exits plus an administration that is favorable toward domestic oil and gas production may boost investment interest from private capital. Private firms may also be more willing to invest in growing volumes compared to public counterparts,” said Dittmar.
Private firms are likely to look beyond the main shale plays to areas like the Rockies or Mid-Continent to find attractively priced deals and avoid competition from public operators. FourPoint Energy made one of the largest recent private acquisitions by acquiring Ovintiv’s Uinta assets in Utah for $2 billion. Previously private equity firm Quantum Energy Partners bought assets in the Uinta and Piceance basins for $1.8 billion.
You must be an Enverus Intelligence® subscriber to access this report.
About Enverus Intelligence Research
Enverus Intelligence ® | Research, Inc. (EIR) is a subsidiary of Enverus that publishes energy-sector research focused on the oil, natural gas, power and renewable industries. EIR publishes reports including asset and company valuations, resource assessments, technical evaluations and macro-economic forecasts; and helps make intelligent connections for energy industry participants, service companies and capital providers worldwide. Enverus is the most trusted, energy-dedicated SaaS company, with a platform built to create value from generative AI, offering real-time access to analytics, insights and benchmark cost and revenue data sourced from our partnerships to 95% of U.S. energy producers, and more than 40,000 suppliers. Learn more at Enverus.com.