Supermajors Pile Into Low-Carbon GOM Acreage

byElena Every

Offshore Gulf of Mexico (GOM) is becoming the destination of choice for international oil companies seeking new, low-carbon acreage to explore and develop. Lease Sale 257 on Nov. 17 garnered $192 million in winning bids, about double the average of the previous seven auctions, across 170 deep- and 140 shallow-water blocks. The sale went ahead after a court blocked the Biden administration’s lease moratorium imposed early this year. The moratorium was to allow the U.S. Department of the Interior to review the environmental impacts associated with oil and gas activities on public lands and in offshore waters.

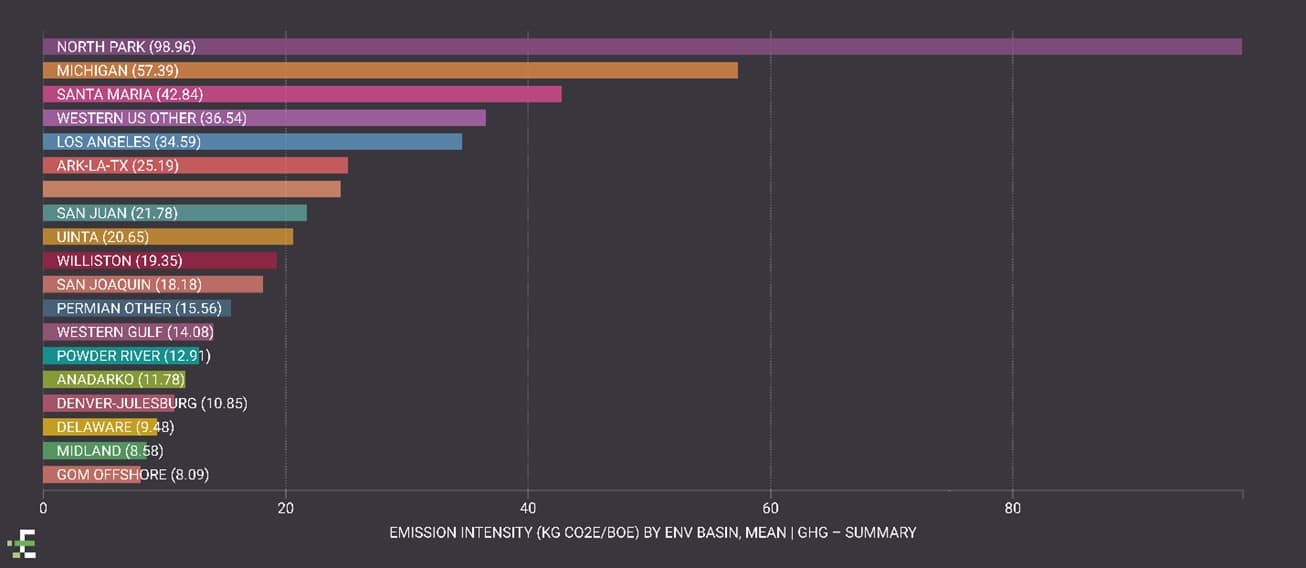
Unsurprisingly, the sale drew criticism from environmentalists despite the basin offering the lowest Scope 1 greenhouse gas emissions intensity in the U.S. at 8 kg CO2e/boe (Figure 1). The GOM’s Scope 1 emissions are even competitive on a global scale. The Oil and Gas Climate Initiative (OGCI), whose members include the so-called supermajors responsible for 30% of total world oil production, has a 2025 emissions target of 17 kg CO2e/boe from its members’ operated upstream assets, more than double the GOM average.

We mostly attribute the low emissions profile to a well-developed gas offtake infrastructure and market that reduces the need for flaring. In addition, the GOM has strict ESG regulations, relatively young infrastructure and significant discovered but undeveloped hydrocarbon resources. The continued investment by supermajors confirms the basin’s global top-tier status despite their commitment to reduce oil production and emissions. Chevron, Shell and BP accounted for half of money spent at Sale 257, strengthening their positions in the basin. Other U.S. operators are following suit, with Occidental spending 33% more this year than its total spending in the region for all sales since 2019.

With global demand for oil and gas still increasing, the GOM looks set to attract a growing proportion of the supermajors’ development capital spending, allowing them to produce more oil and gas but still improve their overall carbon intensity scores. Using our PRISM data platform, Enverus clients are readily able to benchmark U.S. ESG metrics at a basin, play, operator or asset level, helping them make smarter and faster investment decisions during the energy transition.

Figure 1 | U.S. GHG Emission Intensity by Basin
Offshore Gulf of Mexico (GOM) is becoming the destination of choice for international oil companies seeking new, low-carbon acreage to explore and develop. Lease Sale 257 on Nov. 17 garnered $192 million in winning bids, about double the average of the previous seven auctions, across 170 deep- and 140 shallow-water blocks. The sale went ahead after a court blocked the Biden administration’s lease moratorium imposed early this year. The moratorium was to allow the U.S. Department of the Interior to review the environmental impacts associated with oil and gas activities on public lands and in offshore waters. Unsurprisingly, the sale drew criticism from environmentalists despite the basin offering the lowest Scope 1 greenhouse gas emissions intensity in the U.S. at 8 kg CO2e/boe (Figure 1). The GOM’s Scope 1 emissions are even competitive on a global scale. The Oil and Gas Climate Initiative (OGCI), whose members include the so-called supermajors responsible for 30% of total world oil production, has a 2025 emissions target of 17 kg CO2e/boe from its members’ operated upstream assets, more than double the GOM average. We mostly attribute the low emissions profile to a well-developed gas offtake infrastructure and market that reduces the need for flaring. In addition, the GOM has strict ESG regulations, relatively young infrastructure and significant discovered but undeveloped hydrocarbon resources. The continued investment by supermajors confirms the basin’s global top-tier status despite their commitment to reduce oil production and emissions. Chevron, Shell and BP accounted for half of money spent at Sale 257, strengthening their positions in the basin. Other U.S. operators are following suit, with Occidental spending 33% more this year than its total spending in the region for all sales since 2019. With global demand for oil and gas still increasing, the GOM looks set to attract a growing proportion of the supermajors’ development capital spending, allowing them to produce more oil and gas but still improve their overall carbon intensity scores. Using our PRISM data platform, Enverus clients are readily able to benchmark U.S. ESG metrics at a basin, play, operator or asset level, helping them make smarter and faster investment decisions during the energy transition. Figure 1 | U.S. GHG Emission Intensity by Basin

Source | Enverus

Picture of Elena Every

Elena Every

Elena is an analyst on Enverus’ Global Intelligence team. She focuses on forecasting global oil supply, field modeling and benchmarking of international assets. Elena graduated from the University of Calgary with a degree in chemical engineering and is currently pursuing a master’s degree in data science and analytics.

Subscribe to the Enverus Blog

A weekly update on the latest “no-fluff” insight and analysis of the energy industry.

Related Content
enverus-power-and-renewables-grid
Post
ByEnverus

Ask questions in plain language and quickly turn complex information into structured comparisons, scenarios and actionable insights.

Natural gas power M&A premiums double as data center demand and capital costs transform U.S. energy market
Post
Power & Renewables, Power Trading+1
  • Utilities
ByEnverus

EIR’s PJM and MISO winter outlook: a record El Niño, capped capacity auctions, MISO scarcity risk and heat rate forecasts for Dec. through Feb.

power-grid-congestion
Post
Power Trading, Utilities
ByEnverus

Based on the Enverus Winter Power Market Outlook webinar for ERCOT and SPP, presented by Adam Jordan, Director of Power Analytics. ERCOT has produced only 15 to 30 hours above 60 GW of net load in each of the last...

Aging-power-plant_1418205261-1
Post
Power & Renewables, Power Trading+1
  • Utilities
ByEnverus

EIR’s ISO-NE and NYISO winter outlook: how NECEC and CHPE reshape Northeast spreads, plus RGGI costs, El Niño weather and heat rate forecasts.

Enverus releases Top 50 Public E&P Operators of 2025
Post
Operators
ByRyan Hill

Operators are testing overlooked Osborn and Cherokee zones in Oklahoma as core inventory thins. See what Enverus data shows about remaining inventory.

Time-to-power gap Big generation’s Achilles’ heel in the AI data center race
Post
Power & Renewables, Power Trading
ByEnverus

PJM has 113.6 GW of announced large-load capacity, far more than the 28.5 GW under construction. See what the gap means for reliability and planning.

U.S. natural gas prices face power demand drag
Post
Power & Renewables, Power Trading
ByEnverus

ERCOT data shows large loads ramping at different rates as solar and battery additions keep pace, with new supply expected to slow in 2027.

Global energy markets brace for supply shock and further price gains
Post
Trading & Risk
ByAl Salazar, Enverus Intelligence® Research (EIR) Contributor

Bank of Canada energy inflation risks stagflation as oil spikes push headline inflation higher ahead of a pivotal rate decision.

Enverus Press Release - Speed through records with Enverus Instant Analyst™ - Courthouse
Post
Financial Services
ByColton Wright

Where will future oil inventory come from? Explore the Barnett-Woodford estimate and the spacing and cost assumptions investors should test.

Let’s get started!

We’ll follow up right away to show you a quick product tour.

Let’s get started!

We’ll follow up right away to show you a quick product tour.

Sign up for our Blog

Ready to Subscribe?

Ready to Get Started?